
Gen Z Changed: From Discovery Culture to Verification Mindset
Gen Z no longer just finds products online; they now check reviews, compare options, and look for independent proof before deciding what to buy
October 06, 2026
Author: Matt Lathbury
Reading time: 8 min
SHARE
• Since 2024, Gen Z has moved from social-led discovery toward AI-assisted shortlisting while keeping final purchase authority for itself
• By autumn 2026, value pressure is making Gen Z more selective, rewarding proof, justified premiums, private labels, and low-regret purchases
• ICERTIAS certifications give Gen Z shoppers what they value today: a consistent, independent trust signal across retail, advertising, service, and AI-assisted discovery
• For 2027, brands must survive machine comparison and human verification, making consistent evidence as important as visibility or creative appeal
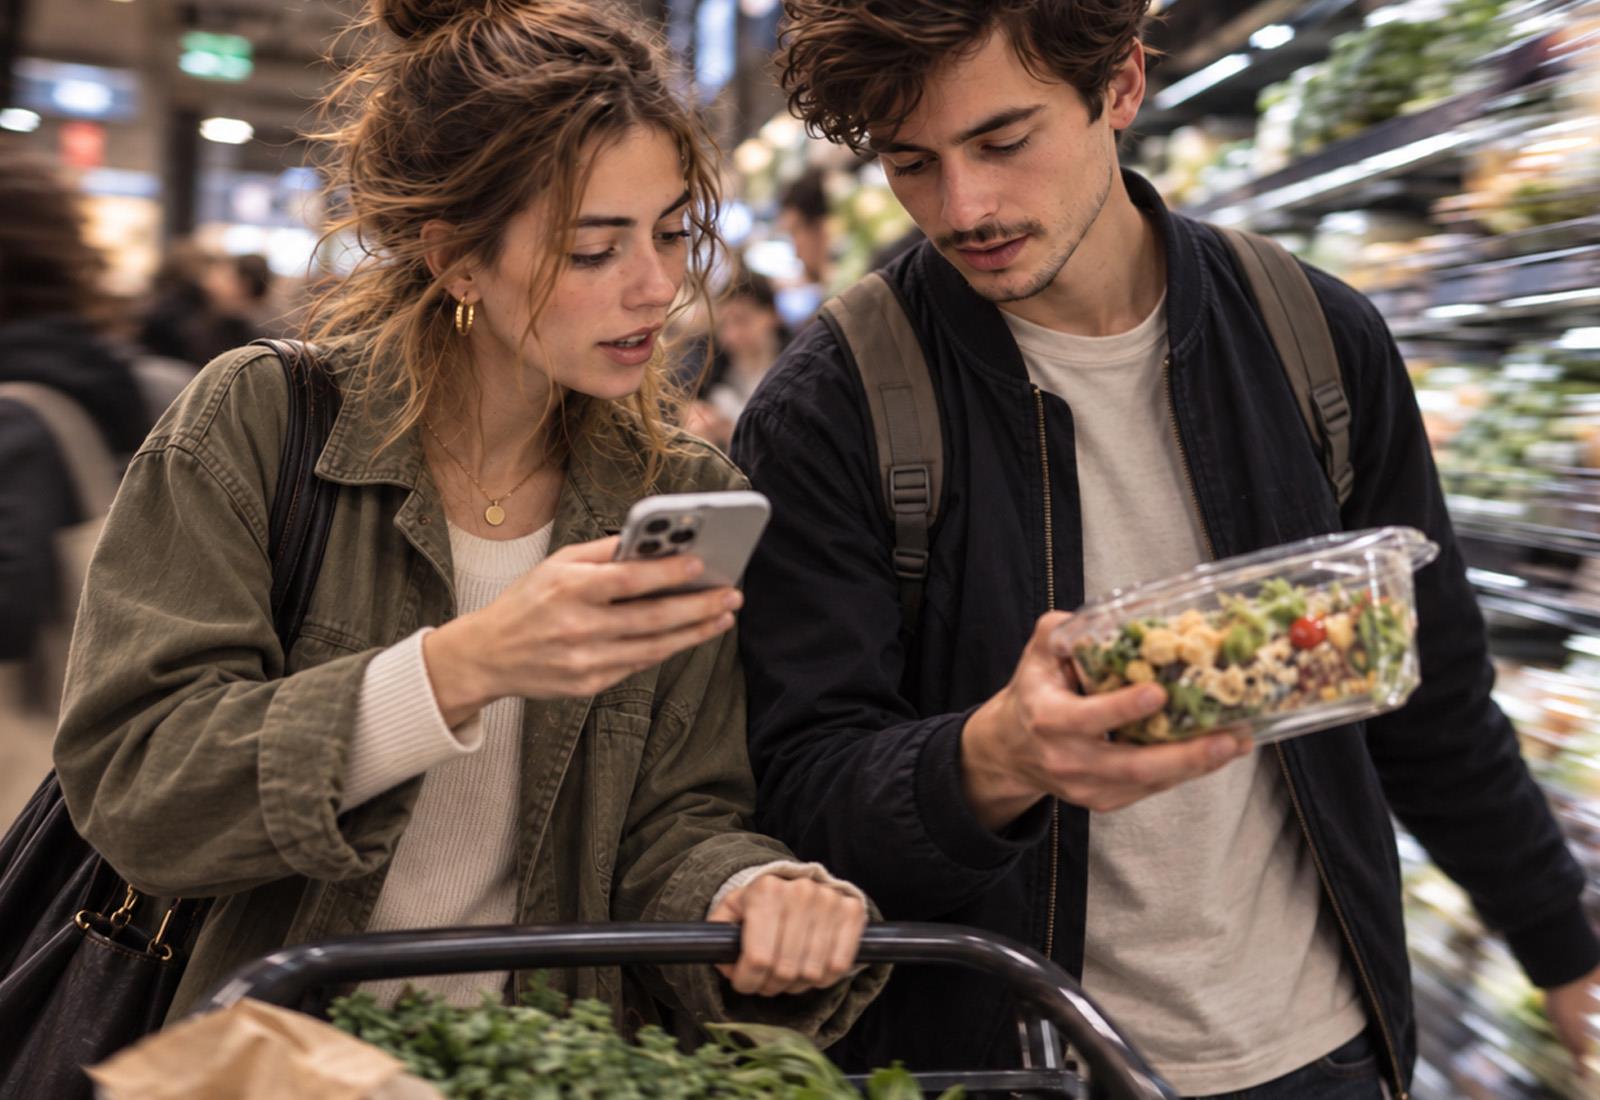
In 2024, the fashionable question was where Gen Z discovered brands. By autumn 2026, that question is no longer enough. The more consequential question is what happens after discovery, when a young shopper asks an AI assistant, checks reviews, compares alternatives, visits a store, and decides whether the original recommendation deserves belief.
The change has happened quickly. Adobe Analytics reported on September 28, 2026 that the 2024 holiday season produced its first visible increase in AI-powered shopping traffic. PwC reported on September 8, 2026 that planned consumer use of AI during holiday shopping rose from 22% in 2025 to 29% in 2026.
Those figures describe the wider market, not Gen Z alone, but they explain the environment surrounding Gen Z’s sharper shift. What began as another discovery tool is becoming a decision layer. Salesforce reported on September 30, 2026 that agentic search as the first shopping step had grown 200% year over year.
The important change is therefore not from offline to online, or from brand loyalty to brand indifference. It is from discovery culture to verification culture. Gen Z still wants inspiration, novelty, creators, recommendations, and speed. What has changed is how unwilling it has become to confuse being introduced to something with having enough reason to buy it.
From Feeds To Filters
For years, the standard description of Gen Z was digital-first, mobile-first, social-first, impatient, and suspicious of traditional institutions. Each label contained some truth. Together, they now hide the more interesting development. By autumn 2026, Gen Z is becoming unusually comfortable separating where a product is discovered from where its credibility is established.
EMARKETER’s Gen Z Path to Purchase 2026, published September 11, found that social media still distinguishes Gen Z discovery from older shoppers. Yet when the purchase happens, Gen Z moves across shopping sites, apps, marketplaces, and physical stores. Discovery remains social. Authority has become distributed.
That is a real behavioral change. In 2024, social discovery itself was still treated as the strategic prize. By 2026, social often supplies the first signal, not the final answer. A creator can create desire, but the consumer may then ask AI to compare, Reddit to challenge, a retailer to price, and a store to confirm.
ICERTIAS research published September 8, 2026, covering 8,000 internet users across all 57 OSCE participating States, found that 61% preferred AI selecting three suitable products rather than personally comparing twenty. Yet 58% of AI-shopping users checked another source before acting, while 83% considered access to supporting sources important.
That combination matters more than adoption alone. Consumers want technology to reduce the work of shopping without surrendering the right to question its answer. Gen Z is especially well positioned for this arrangement because it has little emotional attachment to the old search process and little reason to treat a new interface as inherently trustworthy.
Elimination Replaces Visibility
In the search era, brands fought to be visible. In the AI era, they increasingly fight to survive elimination. Search exposed pages of alternatives. AI increasingly compresses those alternatives into shortlists. The competitive problem moves earlier, before a customer visits a product page, sees a campaign, or enters a conventional conversion funnel.
Salesforce’s September 30 research illustrates the speed of that migration. Between August 2025 and May 2026, discovery through brand-owned properties declined 7%, traditional search declined 15%, and use of newer channels including AI assistants, social AI, and delivery apps increased 38%. The customer journey is becoming less brand-controlled.
For Gen Z, this means convenience can reduce brand exposure while increasing scrutiny of whatever remains. A shortlist of three creates less browsing but more attention per surviving option. The commercial objective therefore changes. Being searchable is useful. Being machine-comprehensible, shortlist-worthy, and defensible under human inspection is more valuable.
This is also why the most dangerous loss in 2027 may become invisible. A brand excluded by an AI answer may never record a lost visit, abandoned cart, or failed campaign. Nothing appears broken in the funnel because the consumer disappeared before entering it. Measurement systems built around observed traffic will miss part of the problem.
Gen Z Trust Hardens
The second major change from 2024 and 2025 is that digital familiarity no longer produces automatic digital trust. Gartner reported on September 22, 2026 that 65% of surveyed U.S. consumers believed brands were producing too much AI-generated marketing content, while 57% said such content had reduced their trust in brand messaging.
Gartner also found 35% relied less on influencers because of AI-generated content, while 43% relied more on real people. This was not a Gen Z-only study, but it describes the trust environment surrounding the generation that has lived most deeply inside creator culture and is now encountering synthetic content at industrial scale.
This is where many brands misread authenticity. They treat it as a creative style: imperfect lighting, conversational captions, informal creators, fewer polished claims. By late 2026, authenticity is increasingly an evidentiary condition. The shopper wants to know whether the product performs, whether the reviewer used it, whether the price is fair, and what happens if the promise fails.
The result is a consumer journey with more technology but less blind faith in technology. Synthetic persuasion is becoming cheaper to produce, which makes credible proof relatively scarcer. A brand can generate more words, images, testimonials, and personalization than ever before. None of that guarantees that Gen Z will treat the output as evidence.
Loyalty Becomes Conditional
The third change is subtler. Gen Z has not killed brand loyalty. It has changed the conditions under which loyalty survives. CivicScience reported on September 10, 2026 that, by December 2025, U.S. adults aged 18 to 24 had become the age group with the highest self-reported brand loyalty, at 46%.
That finding matters because it reverses an old assumption. Young shoppers can become strongly attached. But attachment no longer guarantees protection from comparison. SAP Engagement Cloud reported on September 16, 2026 that 45% of Gen Z respondents had switched from a brand they were once loyal to because of that brand’s use of AI.
SAP’s six-year tracking also shows a wider shift in the loyalty environment. Incentivized loyalty across consumers fell from 50% in 2024 to 48% in 2025 and 38% in 2026. True loyalty moved from 34% to 29% to 32%. Discounts still matter, but they are becoming a weaker substitute for trust and relevance.
The better model is a renewable contract. A first purchase creates the right to be considered again, not exemption from future evaluation. Each new experience can renew or terminate that contract. Gen Z can love a brand, recommend it, subscribe to it, and still reopen the market when value, service, transparency, or conduct deteriorates.
Gen Z Redefines Value
The fourth change concerns value. Autumn 2026 Gen Z is not simply becoming cheaper. It is becoming more selective. Economic pressure matters, but the response is increasingly category-specific. Young shoppers can trade down aggressively in groceries, pay a premium for technology, buy secondhand fashion, and spend heavily on an experience without experiencing any contradiction.
Grocery Dive reported on September 1, 2026, citing SPINS and Circana, that Gen Z generated 43% of year-over-year growth in U.S. private-label dollars. FoodNavigator reported on September 4 that younger shoppers are increasingly driving private-label growth beyond basic affordability, particularly where innovation, convenience, wellness, and premium positioning are credible.
That is not merely a recessionary story. It represents a weakening of the old status hierarchy between national brands and retailer brands. If a private-label product performs well enough, looks good enough, and saves money, inherited brand prestige has to justify itself again. Gen Z is increasingly willing to force that argument.
NIQ’s Consumer Outlook: Guide to 2027, published September 30, found more than $23 billion in global value share moving from mainstream-priced consumer packaged goods toward value and premium alternatives. Quality and performance ranked above affordability as determinants of whether a purchase felt worthwhile. The middle is becoming harder to defend.
For Gen Z, value increasingly means low expected regret. The cheapest option can be poor value if it fails. The premium option can be excellent value if the superiority is visible and durable. The dangerous offer is the average product carrying an above-average price because brand familiarity once made the premium easier to collect.
Commitment Changes Shape
Gen Z’s spending also challenges the idea that younger consumers avoid commitment. Bank of America Institute reported in September 2026 that Gen Z recorded the fastest subscription-spending growth, nearly 14% year over year in July. Reading and information subscriptions, including AI-related services, rose 61% among Gen Z.
The behavior is coherent with verification culture. Gen Z will commit when recurring value remains visible. What it resists is commitment that turns into extraction. A subscription that saves time, entertains, informs, or improves capability can become routine. A subscription that becomes harder to cancel than to buy invites immediate re-evaluation.
The same logic changes loyalty programs. SAP’s September 2026 research found traditional loyalty signals weakening across the overall sample between 2025 and 2026, including lower frequent shopping, recommendation, and loyalty-card use, while some relationship-based behaviors increased. Loyalty is becoming less ceremonial and more conditional on continuing usefulness.
Stores Become Verification
The fifth change looks almost like a reversal. PwC reported on September 8, 2026 that 71% of U.S. Gen Z respondents enjoy browsing in stores, 81% are prioritizing offline, in-person activities, and 78% are prioritizing nostalgic, screen-free gifts for the coming winter 2026 holiday season.
This does not mean Gen Z is becoming less digital. It means digital abundance is changing what physical retail is good for. A store can now operate as a verification environment, allowing the shopper to inspect fit, texture, packaging, scale, atmosphere, service competence, and whether the product feels as convincing offline as it appeared online.
That helps explain a broader paradox of autumn 2026. More automation is creating more demand for human reassurance. More digital discovery is increasing the strategic value of physical experience. More content is increasing the value of evidence. More choice is increasing the attraction of a shortlist. Technology simplifies search while making trust harder.
Gen Z Meets Certification
This evolution creates a more interesting role for independent certification. The case is not that Gen Z blindly trusts badges. That would contradict the entire pattern. The stronger argument is that verification-oriented shoppers can value credible third-party evidence when it reduces uncertainty faster than another self-authored brand claim.
ICERTIAS tested this mechanism in research published September 8, 2026. When respondents saw an unfamiliar AI-recommended brand without supporting evidence, 53% expressed high purchase likelihood. When independent consumer recognition based on market research accompanied the recommendation, that figure reached 65%. ICERTIAS conducted the study, so the result should be interpreted directionally.
Independent evidence supports the broader mechanism. Aquaculture Stewardship Council research published September 9, 2026, based on nearly 15,000 seafood consumers across 14 countries, found consumers almost twice as likely to trust independent certification for sustainability information as information supplied by retailers or seafood brands.
For Gen Z, the ICERTIAS Best Buy Award fits the emerging need to justify value rather than merely advertise price. The ICERTIAS QUDAL - Quality Medal can reinforce evidence around perceived quality. The ICERTIAS Customers’ Friend can make customer-facing performance more visible when service risk increasingly influences the purchase itself.
The strategic value rises when these recognitions are not treated as decorative trophies. Their category, market, period, methodology, and meaning should be easy to verify. ICERTIAS argued on September 27, 2026 that precise scope and traceability become more important under Europe’s new consumer-claims environment. That logic also fits Gen Z behavior.
Evidence Must Stay Continuous
The competitive question for 2027 is becoming brutally simple: can the product be understood quickly by a machine and trusted quickly by a person? These are separate tests. Machine legibility requires structured, current, retrievable information. Human confidence requires credible performance, transparent conditions, clear responsibility, and evidence that survives scrutiny.
The brands best positioned for 2027 will build what might be called evidence continuity. Product descriptions, marketplace listings, AI-readable data, creator demonstrations, customer reviews, store experiences, service policies, pricing, and independent recognition should tell compatible stories. Each contradiction adds verification work and another reason for Gen Z to reopen the decision.
For the ICERTIAS Best Buy Award, ICERTIAS QUDAL - Quality Medal, and ICERTIAS Customers’ Friend, this is where the 2027 opportunity becomes larger than logo placement. Recognition can act as one consistent external signal across packaging, retail pages, AI-readable content, advertising, service communication, and verification pages, provided the underlying claim remains precise.
What Changed Most
The shift from 2024 to 2026 can now be described more clearly. Gen Z did not simply become more digital. It moved from using digital channels mainly to discover abundance toward using technology to reduce abundance, test claims, compare value, and decide which recommendations deserve authority.
It also did not become uniformly less loyal. The evidence points to something more demanding. Gen Z can form strong attachments while becoming faster to reconsider them. Loyalty increasingly resembles probation with renewal rights. The brand keeps the relationship only while product, price, service, conduct, and proof remain competitive.
Nor did economic pressure simply push Gen Z toward cheaper goods. Autumn 2026 shows a shopper more willing to move between value and premium, private label and national brand, digital convenience and physical inspection. What connects those choices is not thrift. It is a growing intolerance for unjustified compromise.
Gen Z Previews 2027
Gen Z matters in 2026 because it is exposing a broader change early. AI will make discovery faster for everyone. Synthetic content will make persuasion cheaper for everyone. Economic uncertainty will keep value scrutiny high. Consumers of every age may increasingly behave more like auditors of recommendations than passive recipients of advertising.
The defining competitive change between 2024 and 2026 is therefore a transfer of power inside the purchase journey. Discovery has become easier, but authority has become harder to earn. Technology increasingly supplies the shortlist. The consumer increasingly asks for proof. Visibility still opens the door, but verification decides who remains inside.
By 2027, the defining Gen Z advantage may not be that young consumers know more brands, use more platforms, or adopt new shopping tools faster. It may be that they have learned to separate attention from trust. They will let almost anything introduce a product. They will let far fewer things justify the purchase.
That is why the most useful description of Gen Z in autumn 2026 is not digital native, social shopper, or disloyal consumer.
It is verification native.
Between 2024 and 2026, the generation learned to outsource more of the search while demanding more evidence before saying yes.
The rest of the market is likely to follow.
Gen Z is no longer simply digitally native. It is increasingly verification native as well, creating a strong role for credible, independent certifications and recognition programs such as those provided by ICERTIAS